2020 – 2026
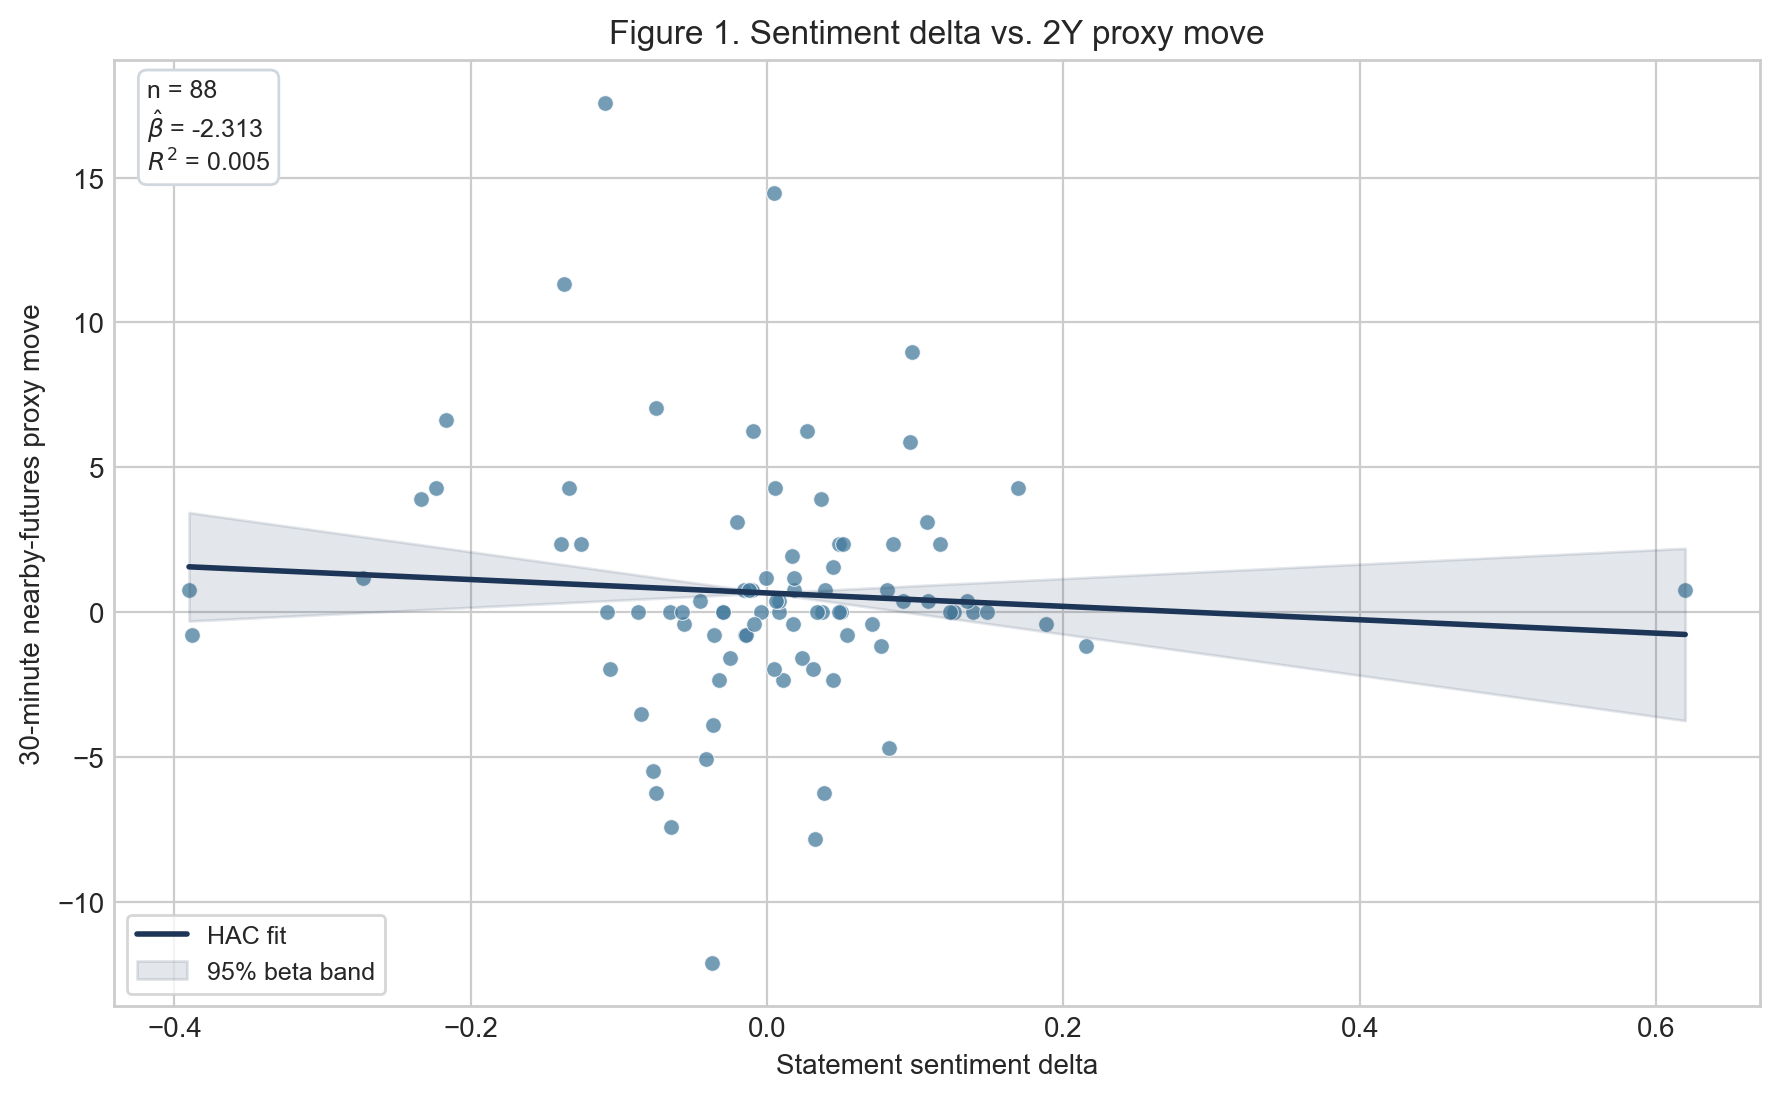
Six standalone studies cover distinct questions in quantitative finance. They examine FOMC statement sentiment against a 2-year yield proxy, intraday spectral signatures, one-second order-book prediction, change-point detection in SPX realized volatility, cross-sectional intraday reversal, and a public-data replication audit of a real-time equity-ML paper.
- Contribution
- Designed and implemented six empirical studies, from data preparation and baseline construction to statistical evaluation and technical reporting.
- Methods
- Event studies, NLP sentiment scoring, signal processing, market microstructure, change-point detection, cross-sectional factor research, replication auditing, bootstrap and significance testing, Python
- Outcome
- A set of careful, reproducible studies, each an honest result about what does and does not hold in intraday, cross-sectional, and risk-signal data.
Alternative Data / Market Microstructure / Risk Signals
Browse research collection →