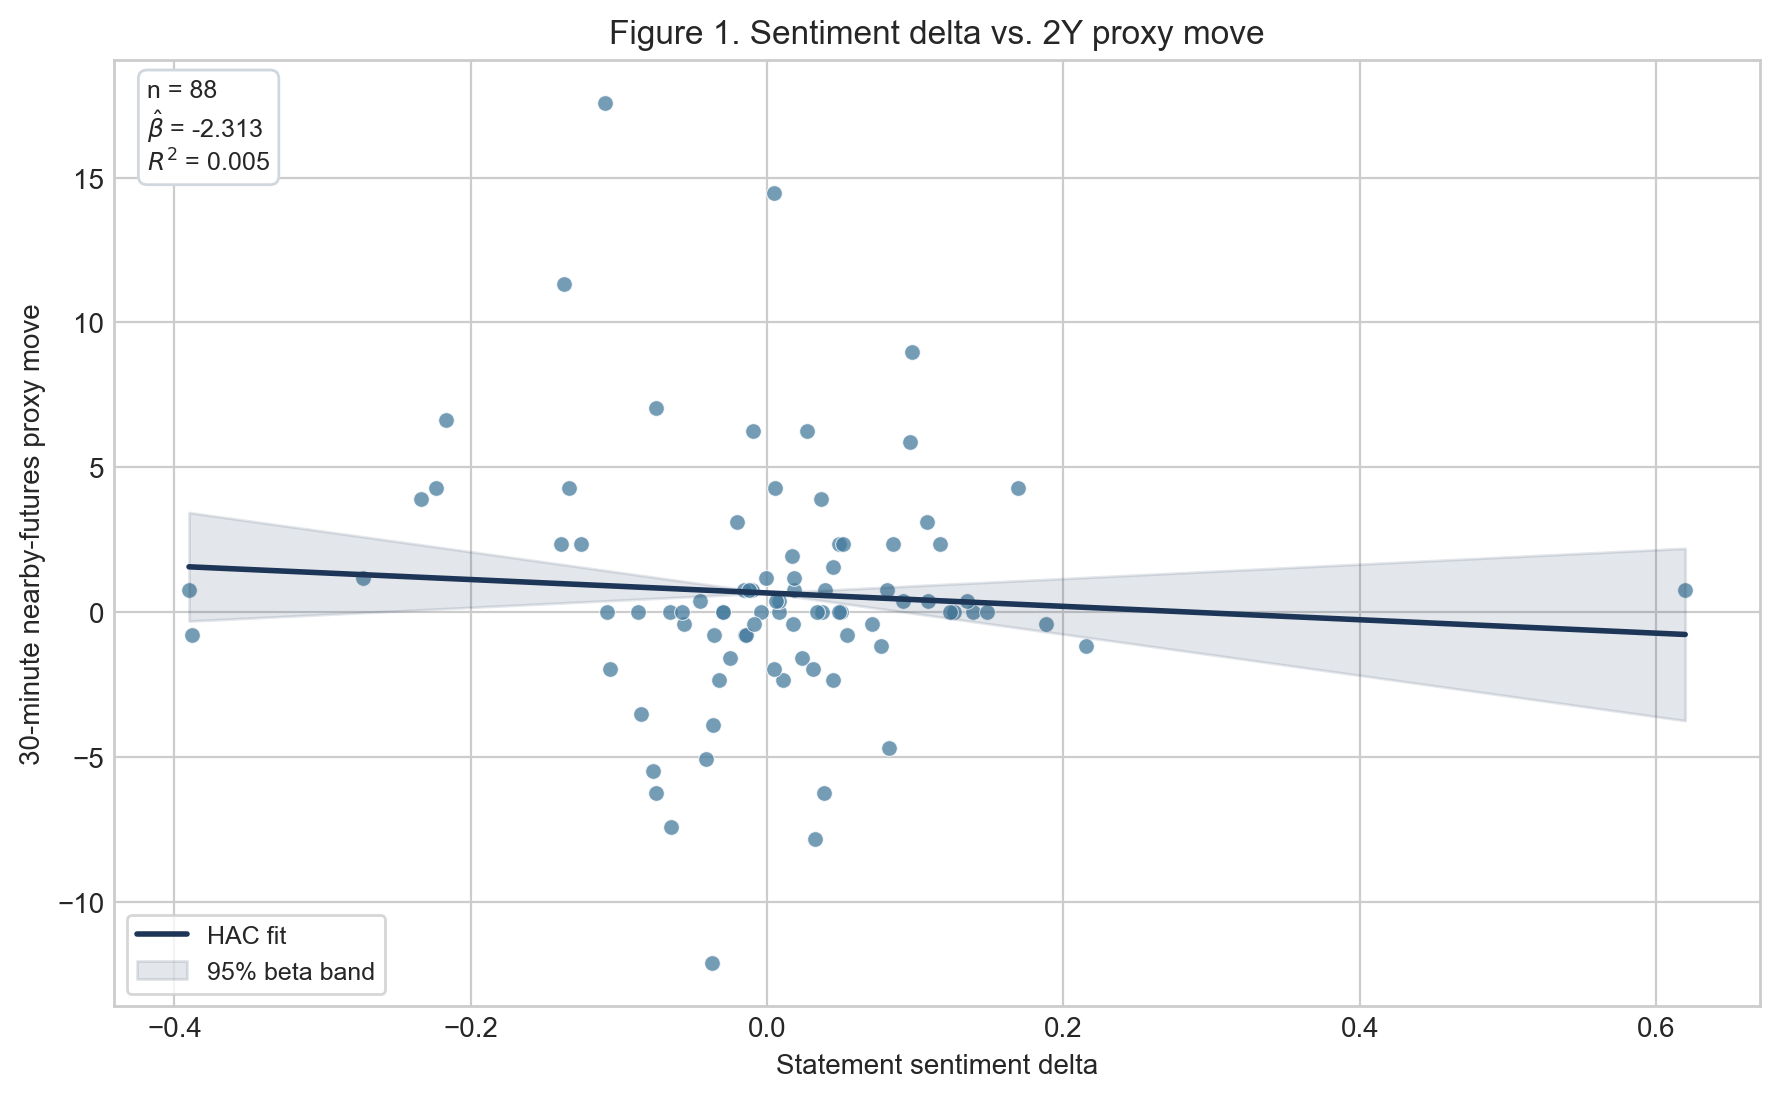
An event-study testing whether FinBERT-coded changes in FOMC statement tone explain 30-minute 2-year Treasury-futures proxy moves around release times.
Contribution
Built the statement-scoring and yield-proxy event-study pipeline, compared sentiment methods, and documented statistical and data limits.
Found no measurable relationship in the statement-read window, while the press-conference window flips to the expected sign but remains statistically indistinguishable from zero.
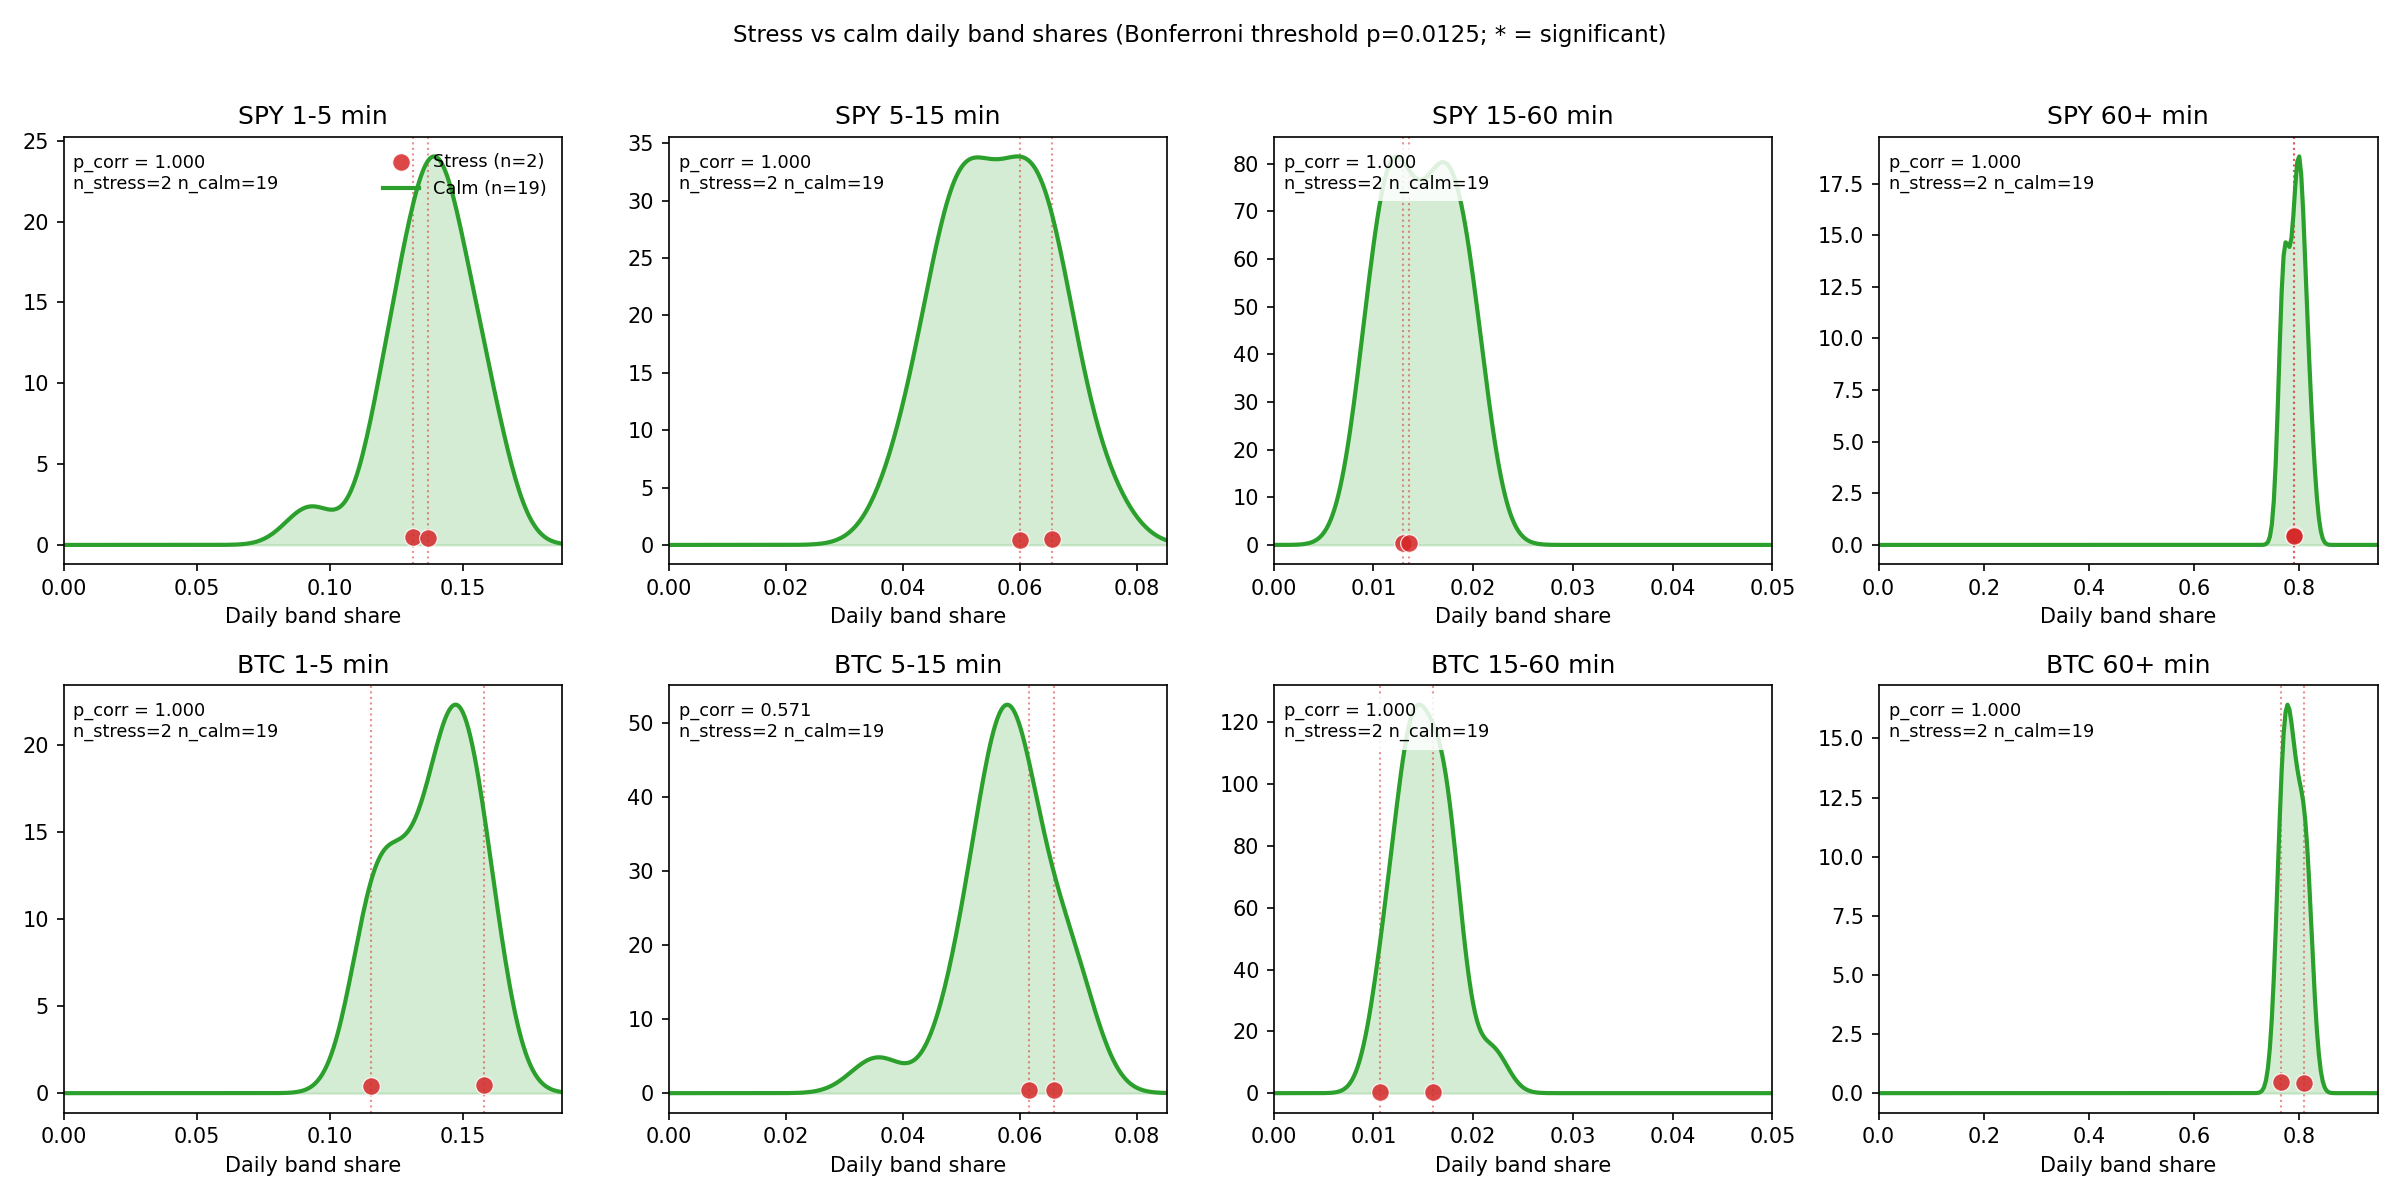
A sample-limited comparison of intraday spectral band shares in SPY and BTC, with a cross-method audit showing how STFT and DWT specifications can dominate the headline asset gap.
Contribution
Built the intraday spectral-analysis pipeline and compared SPY and BTC under matched sampling and signal-processing controls.
Found that the SPY-BTC high-frequency gap is small and specification-sensitive, while the stronger result is a methodological warning about residual versus low-pass band definitions.
Signal Processing / Market Microstructure / Python
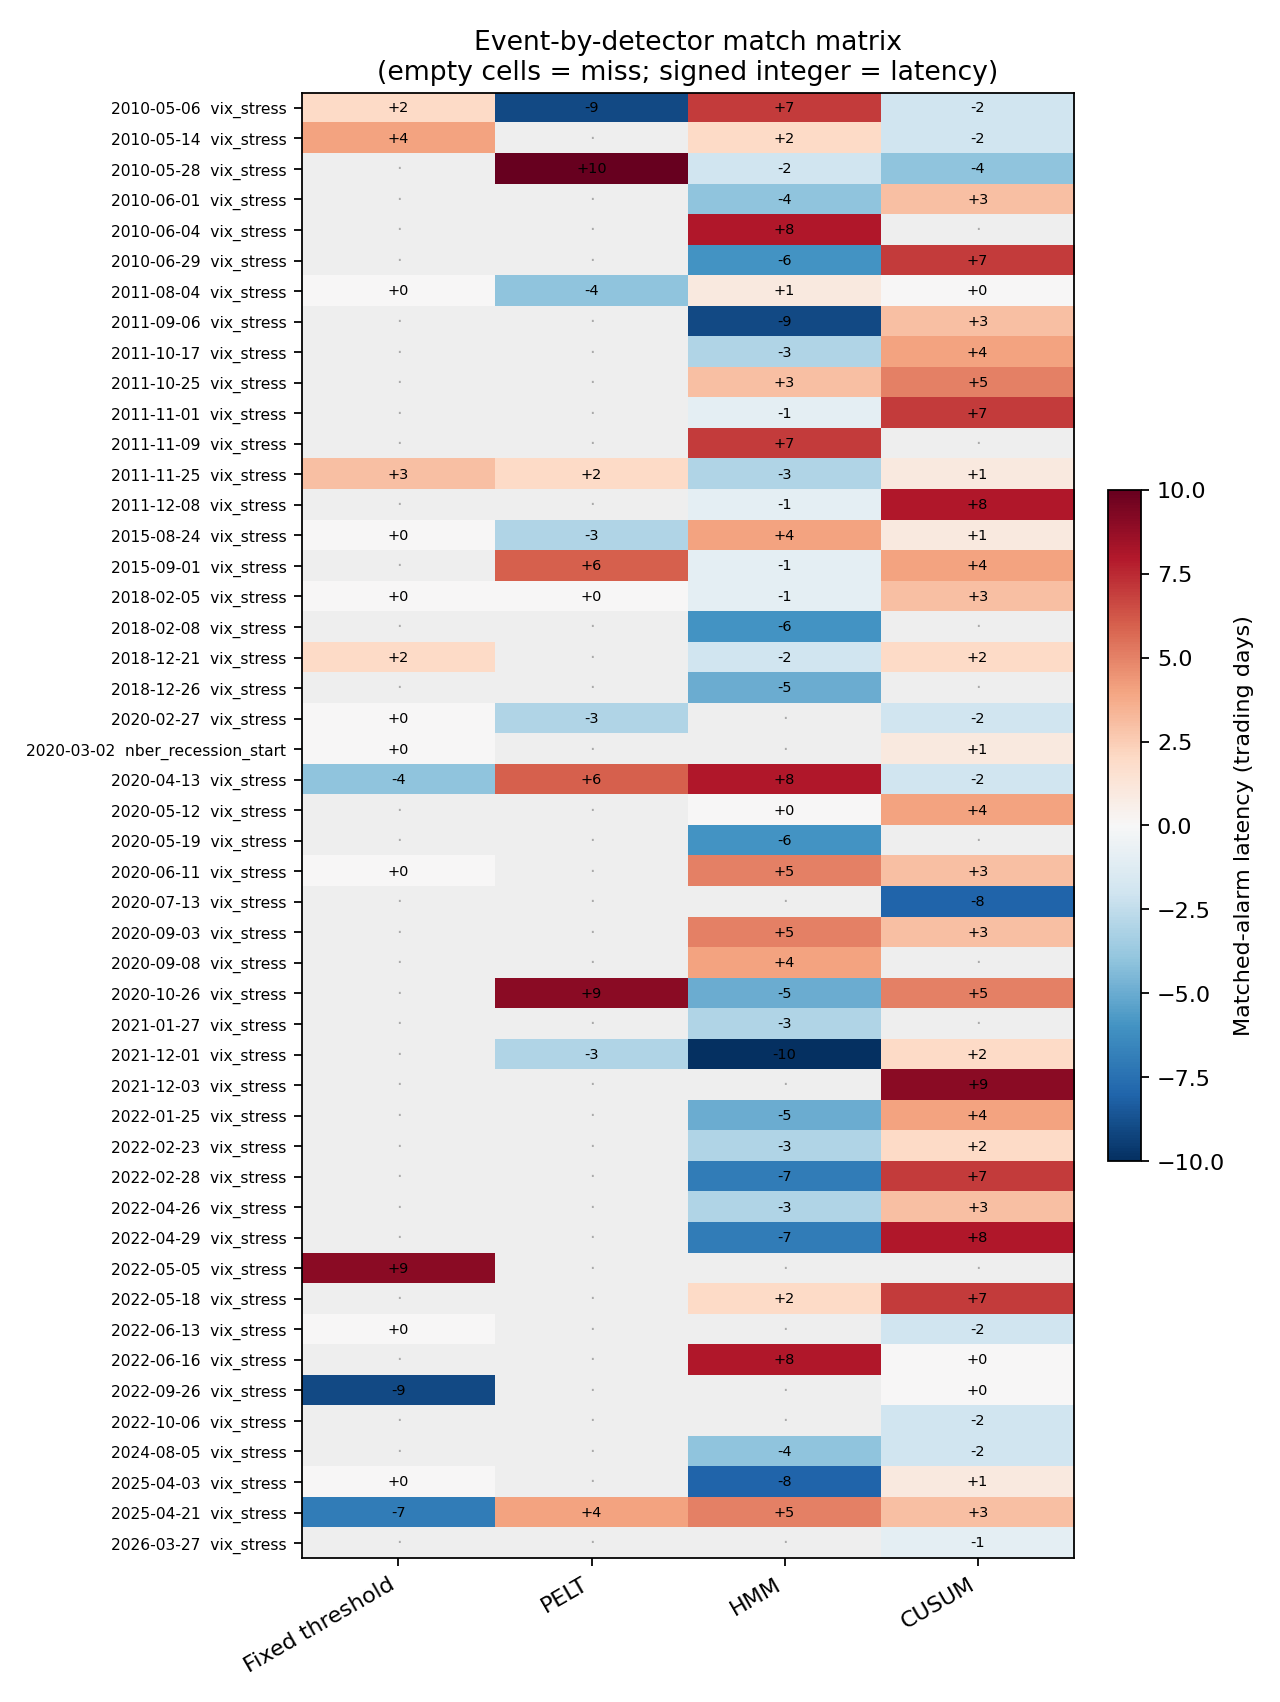
Established under one shared evaluation rule that a fixed-threshold baseline dominates the named detectors on both false alarms and F1, and delivered the reusable bake-off harness that settles the comparison.
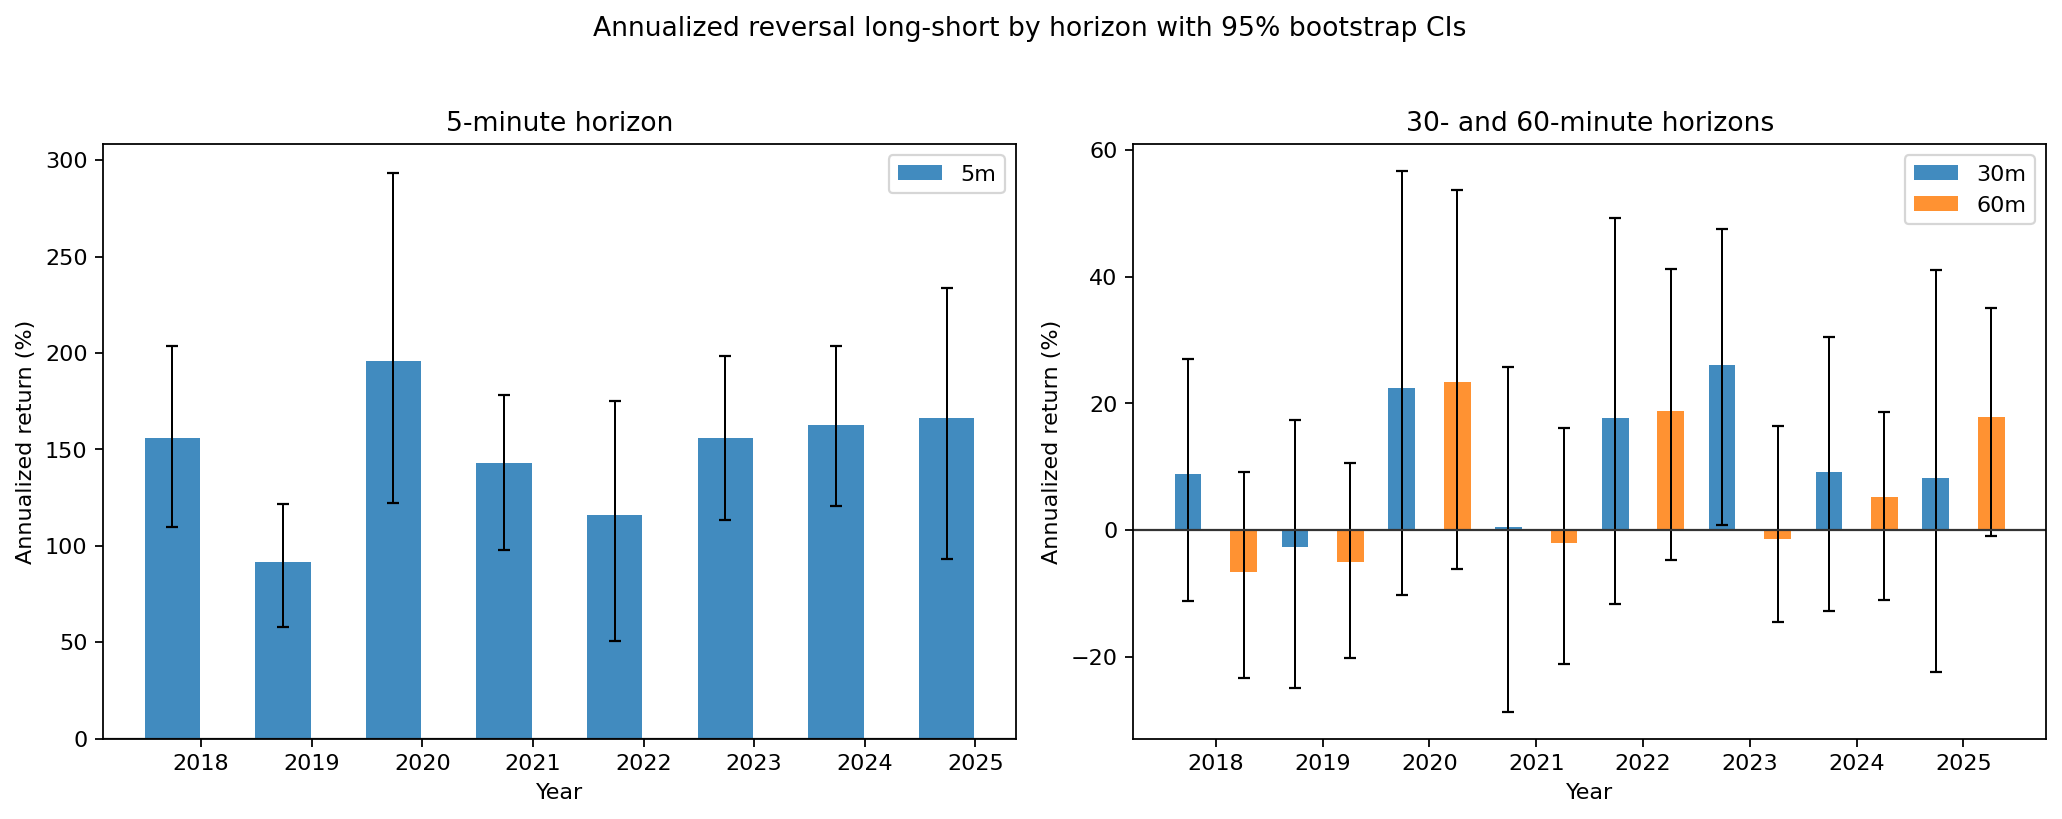
A point-in-time re-measurement of intraday cross-sectional reversal on 373 million minute bars across 529 US large caps, sorted into deciles at 5-, 30-, and 60-minute horizons over 2018 to 2025.
Contribution
Built the cross-sectional reversal study, including factor construction, cost-aware evaluation, and robustness analysis.
Found the effect statistically real but economically dead. It breaks even below half a basis point of round-trip cost and decays inside a single sort interval, which is the signature of bid-ask bounce rather than deployable alpha.
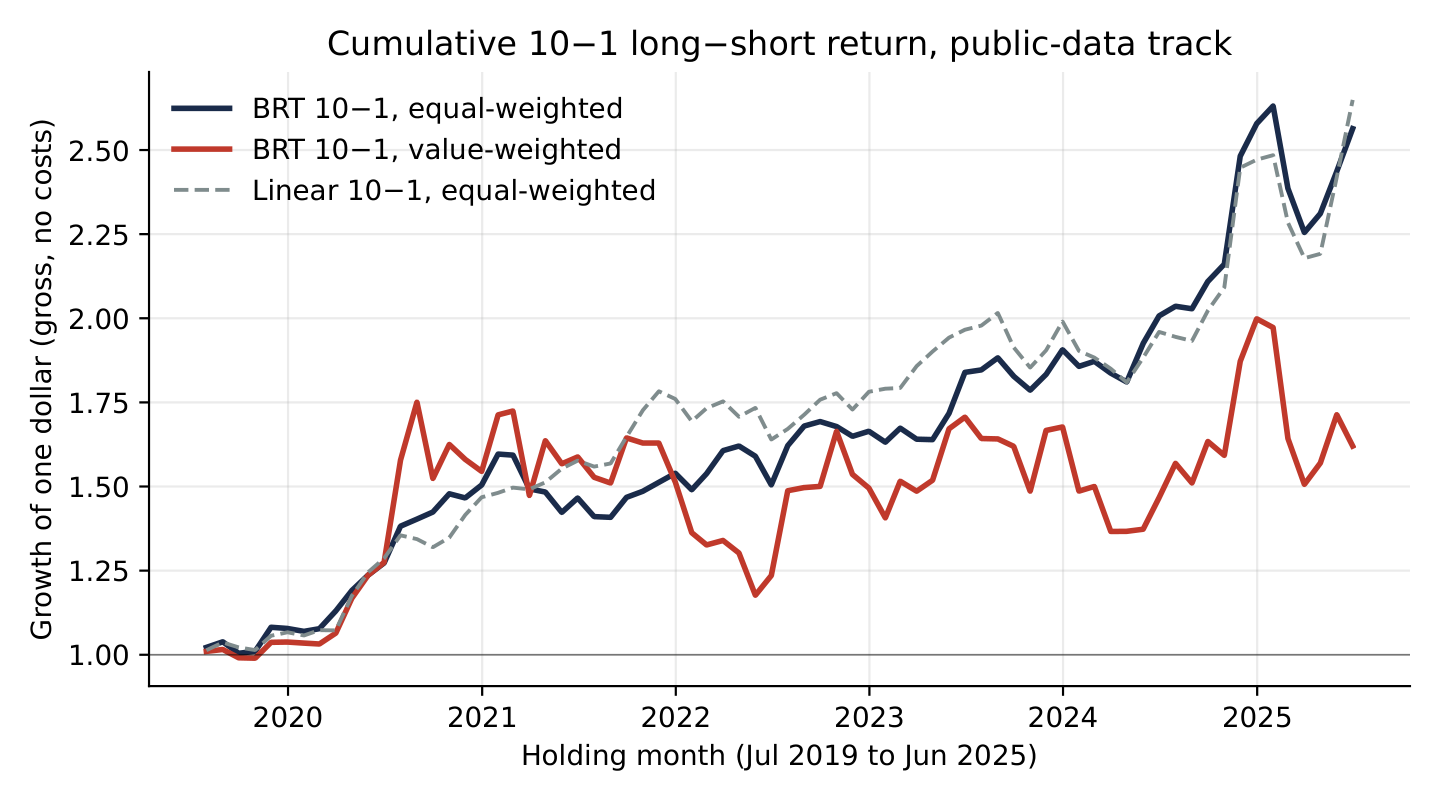
A leak-audited replication attempt on the Chen-Zimmermann sub-analysis of Li, Rossi, Yan and Zheng (JFE 2025), rebuilt as an expanding-recursive real-time pipeline on public, commercial-clean data.
Contribution
Reconstructed a published equity-ML workflow with public data and audited replication limits, controls, and statistical claims.
Methods
Python, boosted regression trees, expanding-recursive validation, decile portfolios, six-factor alphas, SEC EDGAR XBRL fundamentals, ablation and cost overlays
Outcome
Locates the data seam that blocks the paper-faithful reproduction rather than papering over it. The commercial-clean track reports an equal-weighted Sharpe of 1.25 that survives risk adjustment but does not hold under value-weighting.